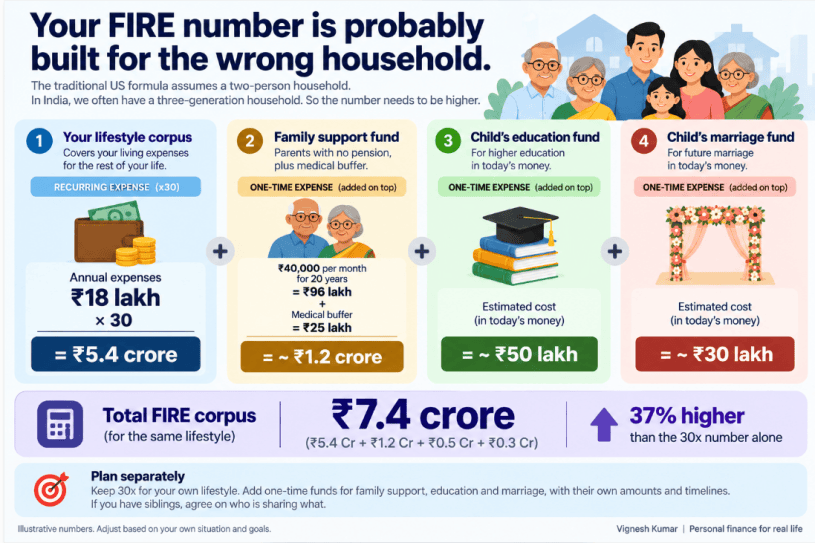
The traditional FIRE approach is simple. Take your annual expenses and multiply them by 25 or 30 to arrive at your retirement corpus. The problem is that the standard calculation only captures the expenses you expect to fund through retirement. It does not automatically account for financial responsibilities that sit outside your own long-term lifestyle.
In India, that can be a significant gap. Our household is often three generations, whether we live under one roof or not. We may be supporting parents, funding a child’s education or planning for a child’s marriage.
Take a household spending ₹18 lakh a year. At 30x, the corpus is ₹5.4 crore. Now add what the basic FIRE calculation leaves out. A family support fund. Parents with no pension, ₹40,000 a month for 20 years, plus a medical buffer. About ₹1.2 crore. A child’s education fund. About ₹50 lakh in todays money. A child’s marriage fund. About ₹30 lakh. The real number is ₹7.4 crore.
That is about 37% higher than the 30x number alone.
In India, we do not always treat these as optional. We assume they have to be done. If we do not plan for them, they can come back as a big liability after we have stopped earning.
Two facts make this hard to ignore:
1️⃣ A 2019 World Bank report said that only 12% of Indians were covered by a formal pension scheme.
2️⃣ World Bank And Milliman says Indias medical cost trend reached 12% in 2024 and was projected at 13% for 2025, more than three times the 4.2% general inflation rate it cites for 2025.
For many of us, our parents retirement plan is us. This is why the FIRE calculator I built works in two steps. First comes the 30x multiplier on your annual expenses. Then comes a separate set of variables for these one-time events, added on top. I think pulling them into the multiplier is a mistake. The multiplier is for expenses that run for the rest of your life. A degree or a wedding happens once. Multiply it by 30 and your number is badly inflated. Leave it out and your number is too small.
My suggestion is three steps:
1️⃣ Keep the 30x corpus for your own lifestyle.
2️⃣ Add each one-time event as its own fund, with its own amount and timeline.
3️⃣ If you have siblings, agree on who is sharing what.
We may be the first generation that funds our parents retirement and our own, without expecting our children to fund ours. Our FIRE number should reflect that.
I write about hashtag#artificialintelligence | hashtag#technology | hashtag#startups | hashtag#mentoring | hashtag#leadership | hashtag#financialindependence
PS: All views are personal
Your FIRE number is probably built for the wrong household.